Here’s the direct answer to how a freelancer LLC owner pays themselves: by default, you take an owner’s draw — you simply transfer money from your business bank account to your personal one. You cannot pay yourself a salary from a single-member LLC unless your LLC has elected S-corp taxation. And whichever method you use, you’re taxed on all net profit whether you withdraw it or not.
That last part surprises a lot of new LLC owners. So let’s walk through exactly how each method works, what it costs you in tax, and when the math changes.
What an owner’s draw actually is
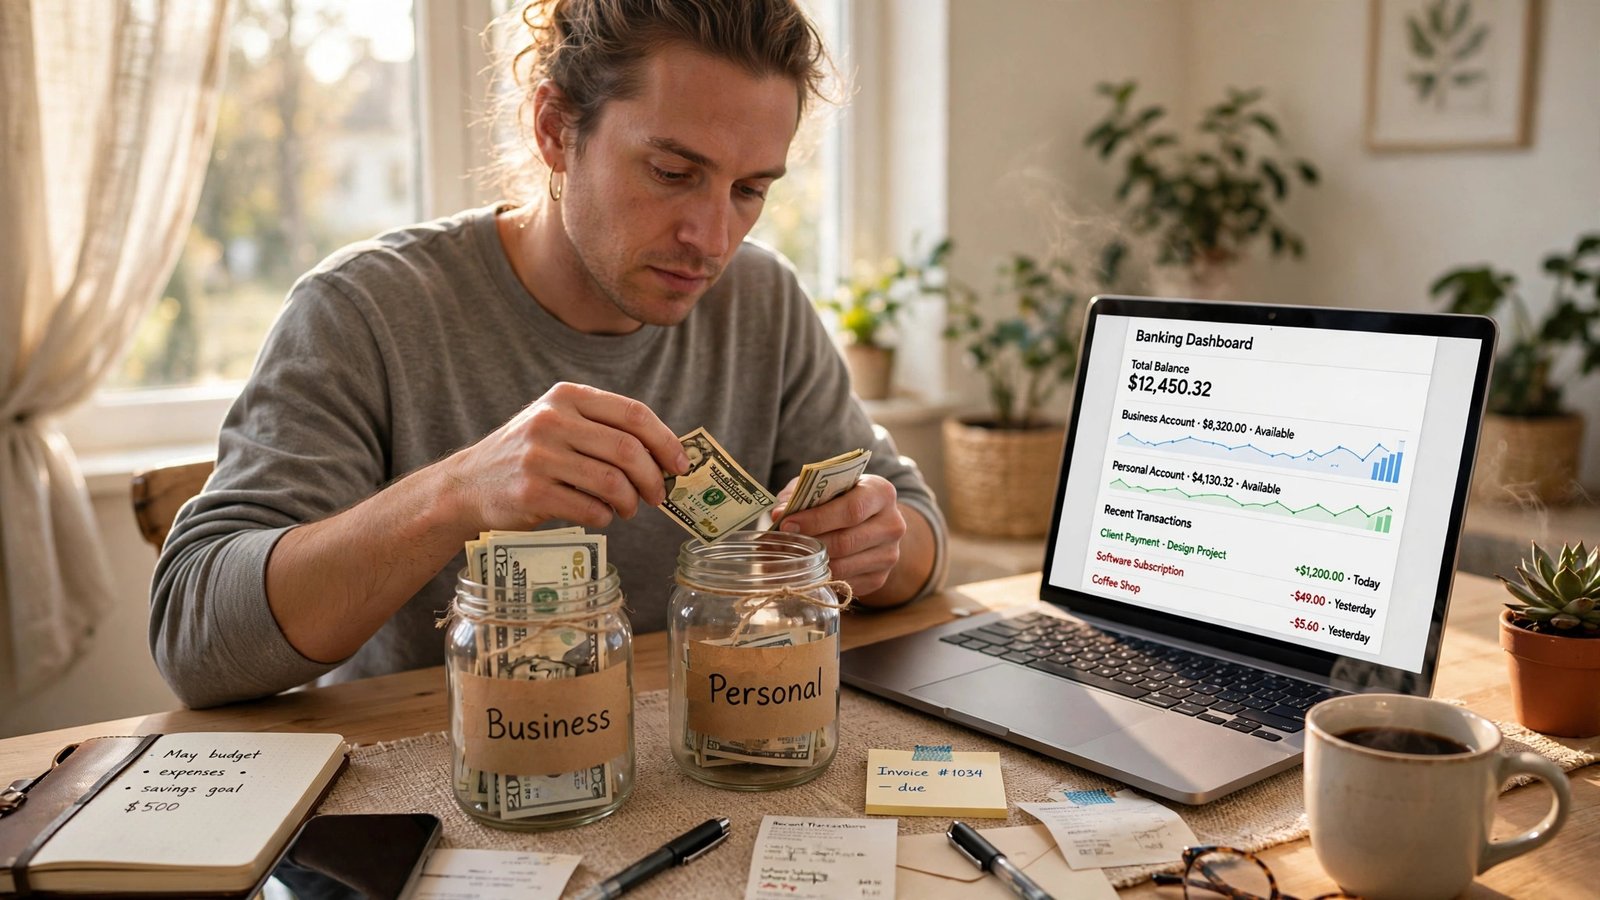
An owner’s draw is the default way single-member LLC owners take money home. There’s no payroll, no pay stubs, no W-2. When you need money, you move it from the business account to your personal account. Most freelancers do this monthly or bi-weekly.
The important thing to understand: a draw is not an expense. You don’t get a tax deduction for paying yourself this way. Your LLC’s taxable profit is calculated as revenue minus business expenses — your draws are simply withdrawals of profit you’ve already been taxed on (or will be at tax time).
This trips people up. They transfer $5,000 to themselves and think “I paid myself, that’s handled.” But no tax was withheld. That $5,000 is still fully taxable, and the IRS expects you to handle the tax through estimated payments. More on that below.
Practical mechanics of a clean draw routine:
- Separate accounts, always. Business money and personal money must live in different accounts. Commingling is the fastest way to damage your LLC’s liability protection.
- Pay yourself on a schedule. Pick a day — the 1st, or the 1st and 15th — and transfer a consistent amount. Treat it like payroll even though it isn’t.
- Label transfers clearly. In your bookkeeping (Wave, QuickBooks, or even a spreadsheet), record every transfer as an owner’s draw, never as a business expense.
- Leave a cushion. Don’t drain the account to zero. Keep at least one to two months of operating expenses plus your tax reserve in the business account.
Why you can’t just give yourself a salary
A single-member LLC taxed as a disregarded entity (the default) is not a separate taxpayer — you and the business are one person for tax purposes. You can’t be your own W-2 employee because you can’t employ yourself.
The only way salary becomes available is the S-corp election: your LLC files IRS Form 2553 to be taxed as an S corporation. Then the LLC can put you on payroll as a W-2 employee, withhold payroll taxes, and you take any remaining profit as distributions. We’ll get to whether that’s worth it.
The 15.3% reality: self-employment tax explained
Every freelancer needs to understand this number: as a default LLC owner, you owe 15.3% self-employment tax on your net business profit — on top of federal income tax.
Here’s how it actually breaks down in 2026:
- Self-employment tax applies to 92.35% of your net earnings (the IRS gives you a small discount to approximate the employer half you’d have if you were someone’s employee).
- That 15.3% is two taxes combined: 12.4% for Social Security (only up to the 2026 wage base of $184,500) and 2.9% for Medicare (no ceiling — it applies to all profit).
- Earn over $200,000 as a single filer and an extra 0.9% Medicare surtax kicks in.
Concrete example: your LLC nets $80,000 after expenses. The SE-tax base is $80,000 × 92.35% = $73,880. SE tax = $73,880 × 15.3% ≈ $11,304 — before a single dollar of federal income tax. That $11,304 is roughly what surprises first-year freelancers into panic every April.
Because as an employee you’d only pay half of the 15.3% (your employer pays the rest), being your own boss effectively doubles this particular tax. The standard advice: set aside 25–30% of every payment you receive for income tax + SE tax combined.
When S-corp election changes the math
The S-corp election’s entire tax benefit is this: distributions are exempt from self-employment tax. Only your W-2 salary carries the 15.3% payroll tax; the rest of the profit passes through to you with only income tax attached.
Example with $120,000 net profit:
- Default LLC: SE tax on 92.35% of $120,000 = $110,820 × 15.3% ≈ $16,955 in SE tax.
- S-corp with a $60,000 salary: FICA payroll tax on the salary = 15.3% × $60,000 = $9,180. The remaining $60,000 passes through as distributions with no SE tax.
The theoretical savings: about $7,775. But the S-corp isn’t free — it adds payroll processing, a second tax return (Form 1120S plus K-1s), and stricter bookkeeping, typically costing $1,200–$2,500 a year. Independent analysis suggests that at $120,000 profit the real net saving after compliance costs can shrink to roughly $3,300.
So when is it worth it? The common guidance: consider the election once your net profit consistently reaches $50,000–$80,000. Below that, the compliance costs eat the savings. Above it, the gap between your salary and your profit is wide enough that the savings clearly win.
Two non-negotiable rules if you elect:
- Reasonable salary is mandatory. You must pay yourself a market-rate salary for the work you do — what you’d pay an outside hire for the same duties. Paying yourself $15,000 on $150,000 of profit to dodge payroll tax is the classic audit trigger. The IRS reclassifies underpaid distributions and applies penalties.
- The deadline is real. Form 2553 must be filed by March 15 to take effect for the current year (or within 2 months and 15 days of forming a new business). Miss it and you wait a year.
Quarterly estimated taxes: the part that ruins freelancers’ Aprils
Because nobody withholds tax from your draws, the IRS requires you to pay as you earn through quarterly estimated tax payments (Form 1040-ES). The 2026 due dates: April 15, June 15, September 15, and January 15.
Skip these and two bad things happen: you get hit with an underpayment penalty (yes, even if you pay your full bill at filing time), and you face a brutal April bill that wipes out your savings. If you remember one thing from this article: the quarterly deadlines matter more than the draw-vs-salary debate.
A simple method: every time a client pays you, immediately move 25–30% into a separate savings account labeled “taxes.” When a quarterly deadline arrives, you pay from that account and never feel it.
A practical monthly pay-yourself routine
Put it all together into a monthly rhythm that takes about 20 minutes:
- Invoice day (1st of the month). Send all client invoices. Record expected income.
- Tax reserve. For every payment that lands, immediately move 25–30% to your tax savings account. Do this first, every time — not at month’s end when it’s “whatever’s left.”
- Pay yourself (1st and 15th). Transfer your fixed draw amount. Same dates, same amount. If revenue was great, resist the urge to splurge-draw; if it was thin, don’t skip — adjust the amount deliberately instead.
- Business buffer check. After your draw, confirm the business account still holds your operating cushion (rent, software, insurance). If it’s shrinking two months in a row, your draw is too high.
- Bookkeeping. Log every transfer. Five minutes a month now saves five hours of forensic accounting in April.
- Quarterly review. Every quarter, compare actual profit to your draw rate and estimated payments. Adjust both before the next quarter rather than playing catch-up.
This routine works for draws today and still works if you later elect S-corp status — the only change is that part of your pay runs through payroll software.
If you’re earning platform income (ad revenue, creator payouts) through your LLC, the same mechanics apply — the draw process doesn’t change, just the income source. For those earning through Google AdSense, the approval requirements cover what a new site needs before revenue starts.
Related: Getting an EIN for Your LLC Without an SSN (2026)
Frequently Asked Questions
Can a single-member LLC owner take a salary?
Only if the LLC has elected S-corp taxation by filing Form 2553. Under the default tax treatment, you take an owner’s draw, not a salary — there is no payroll, no withholding, and no W-2.
Is an owner’s draw taxable?
Yes. A draw itself isn’t an expense and isn’t taxed at the moment of transfer, but you’re taxed on all of the LLC’s net profit whether you withdraw it or not — through income tax plus 15.3% self-employment tax.
At what income does an S-corp election make sense for a freelancer?
The common rule of thumb is $50,000–$80,000 in consistent net profit. Below that range, the added payroll and filing costs (roughly $1,200–$2,500/year) usually consume the SE-tax savings.
How much should I set aside for taxes as an LLC owner?
25–30% of every payment is the standard target, covering both self-employment tax (15.3%) and federal income tax. Move it to a separate savings account the day you get paid.
When are quarterly estimated taxes due in 2026?
April 15, June 15, September 15, and January 15 (2027). Missing them triggers an underpayment penalty even if you settle your full tax bill at filing time.
This article explains general tax mechanics for informational purposes — it’s not professional tax advice. Tax rules have edge cases and change, so run your specific situation by a CPA or tax professional before making structural decisions.
Sources: S-Corporation tax guide (2026), Quarterly taxes: who pays & when they’re due